Capacity and headroom
Does the business have enough funding available for its current trading position and plans?
- Additional working capital
- Seasonal or growth headroom
- Funding for stock, orders or investment
 Business finance partner
Start your enquiry
We review and optimise your funding position, structure the requirement and make focused approaches to lenders whose appetite is aligned.
Your funding position
Most established businesses already have some form of funding. The question is whether the current position provides the capacity, flexibility and structure the business now requires.
Does the business have enough funding available for its current trading position and plans?
Can the existing facilities respond as requirements change?
Is the overall funding arrangement appropriate for the business?
We consider these factors together and advise whether existing funding should be retained, supplemented or replaced.
Finance solutions
Whether you need more working capital, investment for growth, new equipment or support with an existing funding arrangement, we can help identify and access an appropriate finance option.
Release cash from invoices, fund stock, purchase orders and supplier payments.
Fund expansion, acquisitions and other investments in the future of your business.
Explore all growth finance →Purchase or refinance machinery, equipment and commercial vehicles.
Explore all asset finance →Review existing borrowing or complete a time-sensitive commercial transaction.
Explore all refinancing options →How funding can work
See how invoice, trade, asset-based finance and refinancing can address practical business requirements.
 Invoice finance
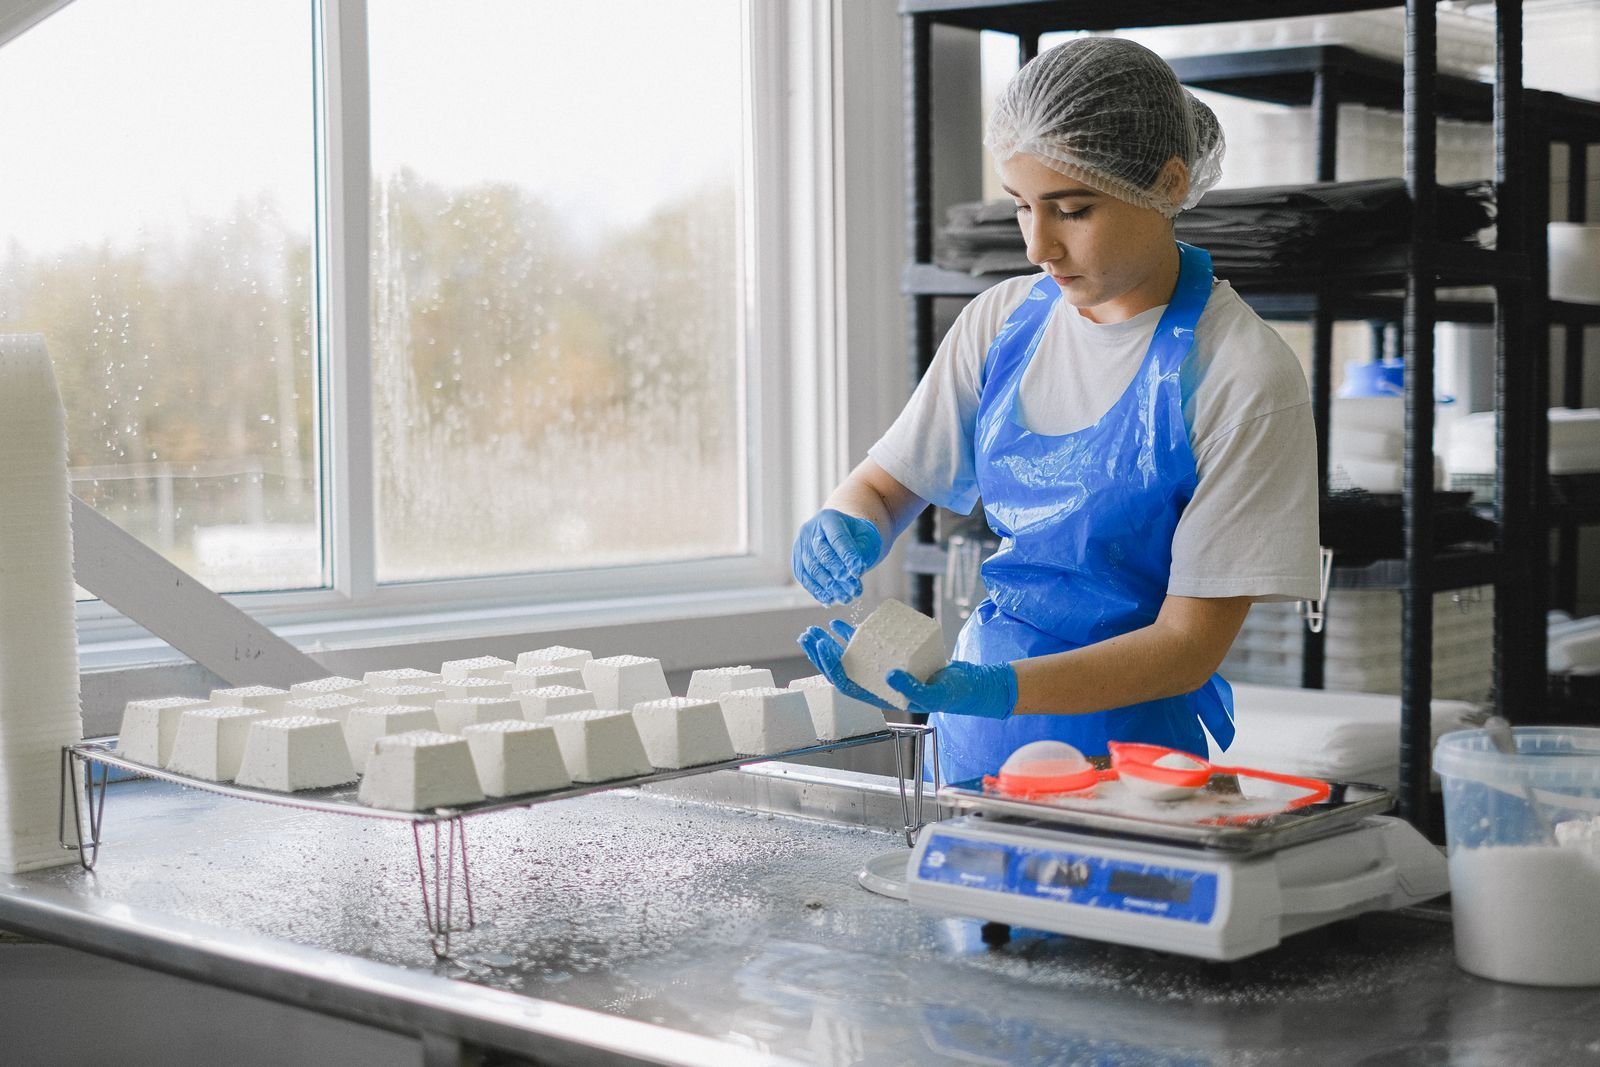
A food producer supplying national retailers used invoice finance to release working capital from invoices issued on payment terms of up to 90 days.
Read full scenario →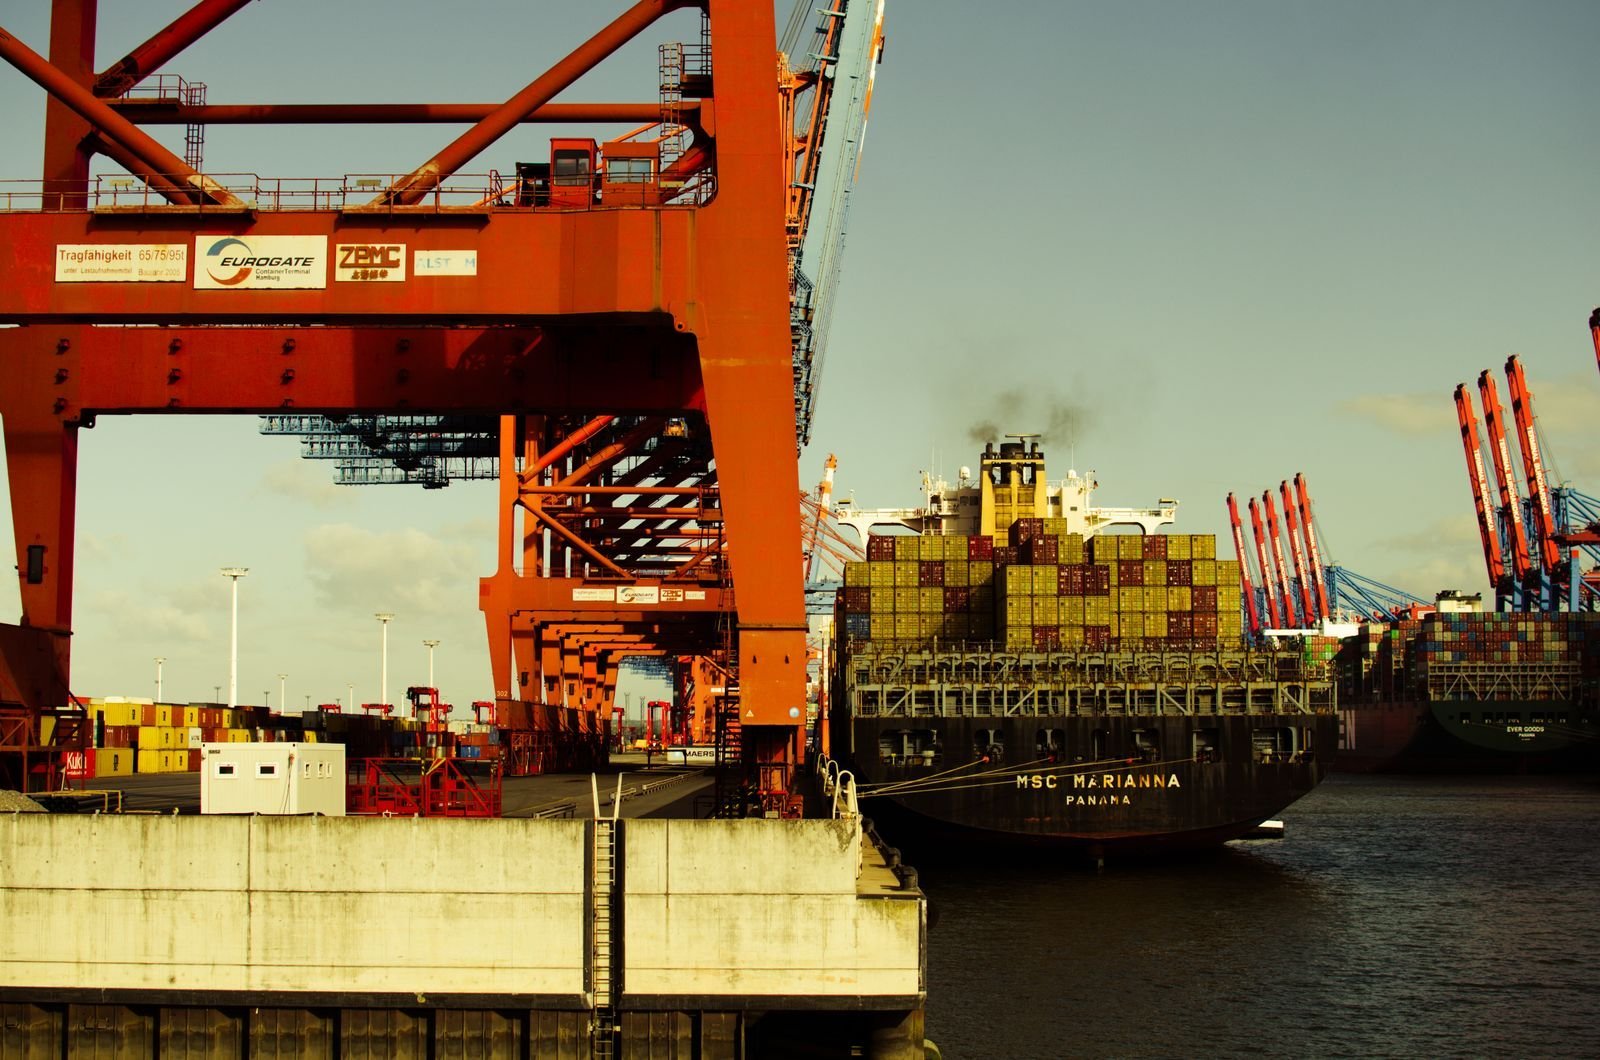 Trade finance
A trading business used a revolving facility to pay overseas suppliers that required payment before goods were shipped.
Read full scenario → Asset-based lending
An engineering business released equity tied up in machinery and added revolving working capital to support expansion into new markets.
Read full scenario → Refinancing and restructuring
An established business refinanced several facilities into a more manageable structure with additional headroom and clearer repayment terms.
Read full scenario →How it works
We bring assessment, structure, lender access and transaction support together in one process. We do not circulate your application widely: any approach is focused, discussed with you and made only with your permission.
We assess your business, its working-capital position, existing facilities, available assets and plans.
We consider the funding routes available to your business and explain the likely costs, compromises and implications of each.
We build a credible funding case and approach selected lenders whose current criteria and appetite fit the requirement.
We manage lender discussions on your behalf, compare proposals and support you through due diligence, negotiation and completion.
About us
Our background spans commercial lending and the development of finance products for banks and fintechs. We understand how lenders assess trading performance, cash generation, security and repayment capacity, where applications can stall and what decision-makers need to see when reviewing an application for credit.
Discuss your funding →
Our core funding review, lender approach and transaction-support service is paid for by the lender if funding completes. Commission can vary by lender and product. We explain the amount or basis of our commission before completion, together with lender interest, fees and other facility costs. Our lender panel does not include every provider in the market.
FAQs
We are generally best placed to support established UK-incorporated businesses with annual turnover above £500,000 and funding requirements from £50,000. We may also consider smaller or newer businesses where the requirement is supported by property, equipment, invoices, confirmed orders or other business assets. We do not accept applications from consumers, sole traders, unincorporated partnerships or individuals borrowing personally.
No. We do not charge your business for our core funding review, lender approach and transaction-support service. We receive commission from a lender if funding completes. Commission can vary by lender and product, and we explain the amount or basis before completion.
No. We provide commercial funding advice and act as a broker for UK limited companies. Lenders make their own credit, pricing and approval decisions.
No. We focus on lenders we believe may have relevant appetite and seek your permission before making introductions.
Yes. We review existing facilities, available headroom, flexibility, security, repayment terms and cost. We can advise whether the current arrangement should be retained, supplemented or replaced, then approach suitable lenders with your permission where a change is appropriate.
Our typical client
We are generally best placed to support established UK-incorporated businesses with annual turnover above £500,000 and funding requirements from £50,000 for working capital, growth, equipment, acquisitions, refinancing or commercial bridging.
We may also consider smaller or newer businesses where the requirement is supported by property, equipment, invoices, confirmed orders or other business assets.
Start your enquiry
A few short steps give us enough to begin. No documents are needed at this stage.